 Skip to content
BLOG
“Pay rent? You can pay for a home”: Ani Miller on Salud, Dinero y Amor
Ani Miller explains to Liliana Pérez how to build credit, make the most of your taxes and plan the purchase of your first home.
July 10, 2025 · Interviews · Leer en español
On the podcast Salud, Dinero y Amor with Liliana Pérez, Ani Miller shared concrete strategies on credit, taxes and real estate, along with the routines that help her every day.
What we talk about
- Her financial education, from her family home to Venezuelan banking
- How to build and protect your credit score
- Taxes done right, depreciation and the credits people miss
- Strategies for buying your first home without buying on emotion
- Budgeting, sacrifice and her three daily routines
The full conversation
On the podcast Salud, Dinero y Amor (Health, Money and Love), host Liliana Pérez devoted an entire episode to money, with the goal of making the complicated simple. Her guest was Ani Miller, CEO of Ani Miller Services, whom Liliana introduced as someone who brings together "everything you can have on the financial side": taxes, real estate, mortgages and insurance. In almost an hour of conversation, Ani shared how she got into finance, how she started from zero in the United States and how her company was born, and answered practical questions in detail about credit, taxes, insurance, buying a home and family budgeting.
Finance from inside a bank
Ani explained that finance has always been an important part of her life, since she was a child. In Venezuela there is a program, INCE, that helps recent high school graduates learn an occupation. Ani graduated at 16 and the program placed her at a financial institution, where she started as an intern while studying at the university at night.
There she began to understand finance from the inside: a bank makes money by lending it, so that people manage it optimally, get a benefit from it and at the same time can repay the bank with interest. That, she said, was the foundation of her training.
How she discovered her passion
Liliana commented that many people work at something that earns them money but does not excite them, and that before recording she had noticed Ani's eyes lighting up when she talked about this topic. She asked when Ani discovered that finance was her calling.
Ani said it was many years ago in Venezuela. She worked in banking for 12 years, from 16 until 28, when she came to the United States. During that time she did it all: intern, making copies, business advisor, executive, manager and, finally, vice president of business.
That grain of sand, that loan the bank gave them, allowed them to plan ahead and grow in the future.
She recalled seeing how a tiny company she had supported grew to have ten branches, and being part of that growth fulfilled her as a person. She also grew up with her family's example: her mother is a business administrator and her father has between ten and twelve rental properties in Venezuela. That family schooling, plus the university and daily contact with the bank's clients, was the "switch" that convinced her this was her calling.
2016: starting from zero with the apps
Ani arrived in the United States in 2016 and did not start out in her field. Like many immigrants, she did what she had to do: she worked for practically every app out there, for deliveries, food and ride-hailing. That surrounded her with people who, like her, were trying to get ahead.
A coworker from that time gave her a piece of advice that changed her path. When she mentioned that she wanted to learn English, he recommended that she not go to the free schools, but make the effort to pay for a good school to get fast results. The cost was considerable, but she trusted the recommendation.
To be able to attend, she worked deliveries until midnight and studied in the morning, Monday through Thursday, because she wanted to go with a fresh mind. She did a full year of grammar and then another year of conversational English, to lose the fear of not being understood. She acknowledged that a full-time job would not have allowed her to do it.
I took the little stones that came my way, instead of seeing them as an obstacle, as the path I had to travel to get to what I wanted.
Her goal, she said, was to work in finance again.
The IRS letter: a five-hour wait
Liliana asked what the first step on that path was. Ani explained that her company was born from her own experiences as an immigrant. In her first year in the country she hired someone who had been recommended to her to do her taxes and stopped worrying about it. Then a letter from the IRS arrived, something that, in her view, is one of the biggest fears of people living in the United States.
She did not understand the letter and did not speak English yet, so she called the person she had paid. She received no help at all. She went to the office, they made her wait five hours and no one saw her.
That day she wondered how many people must be in the same situation, having paid for a service that did not show up when they needed it. She decided to look for an institute where she could learn everything about taxes, starting with resolving her letter. They helped her, she requested an appointment, went to the IRS in person and resolved the matter herself. Within a week and a half she had received her refund.
With that knowledge, she offered to do her relatives' taxes without charging them. They all accepted, although some insisted on paying her. She started telling her friends what had happened to her, that she had resolved it and that she now had a license to prepare taxes. Her friends and family trusted her, and that is how the company was born, at first with taxes only.
The car with a balloon payment
Then came another experience. Ani bought a vehicle believing she had made a good deal, and later a police officer crashed into her on the highway. When she went to the dealership to trade in the car and asked how much she owed, she was told she owed the full vehicle, even though she had been paying for two years. The contract had 71 interest payments and a balloon payment with the principal.
Since she drove her children around in that car, she could not keep using a wrecked vehicle, so she traded it in and learned everything about financing at dealerships. Since then she has also offered that service, with one central piece of advice: do not go to the dealership alone.
- Before going, you run the numbers and negotiate.
- The dealership tends to drag out the process until the client, after many hours, is so tired they sign whatever is put in front of them.
- If the deal is put together beforehand, the client sets the terms: if those numbers are reached, you go and sign; if not, you do not go.
- Knowing how to read the numbers lets you spot charges they are adding that you will not even need.
Liliana asked whether you really can change a dealership's initial offer by going in prepared. "Yes, you can," Ani replied.
Pay cash for the car or finance it?
Liliana asked whether it is better to pay for the car in full or finance it. Ani answered that it depends, but that in the United States your credit score is very important and you have to build it. People who are afraid of all debt rarely move ahead financially; what matters is telling good debt from bad debt.
Her reasoning was this: if no bank has trusted you with more than a credit card with a low limit, who is going to lend you half a million dollars for a house or $50,000 for a car? You would be a very risky person. That is why, for clients who do not want to pay interest, she suggests a strategy:
- Finance the car and make principal payments to pay it off quickly, for example in a year.
- That way they build up at least 12 months of on-time payments that show the bank they are reliable.
- After that year they are no longer a "first-time buyer" and can access lower interest rates.
In the United States, a person with an excellent credit score is worth more than a person who has $5 million in an account.
She said she knows people who are millionaires in their bank accounts and still cannot get credit approved, because the U.S. system works differently from the one in our countries.
Indexed universal life insurance (IUL)
Liliana moved on to another tool Ani handles: insurance. Ani explained that, with social media, everyone talks about insurance now, but each person has to look at what fits their situation. She has an IUL policy for herself and for her children, and she recommends it to many clients.
She said she does not like term insurance, because as long as you do not die nothing happens: basically you are buying the insurance for your beneficiaries. And she asked what happens to you if you reach 70 and have to wait for your children to support you. As she explained, an IUL is different:
- It is life insurance: if you pass away, it pays your beneficiaries.
- If you get sick, you can access the money early.
- Part of the money builds value over time, with compound interest, so your money works while you sleep.
She clarified that, since it is a policy, it should not be called an investment, although an indexed policy can allow you, in her words, to be your own bank. She stressed that you do not need to put in a lot of money each month: the amount depends on each person's profile and situation, but you have to start. And if you have financial responsibilities or properties, insurance keeps your children from losing them if something happens to you.
She gave an example of her own: she bought an office through an SBA loan, which required her to have a life insurance policy. Instead of a term policy, she chose an IUL, with the lender as beneficiary, so that if something happened to her the policy would pay and the office would stay with her children.
Liliana admitted it was the first time anyone had told her about this type of policy and that many people who sell insurance only offer term policies.
If you pay rent, you can pay for your home
Liliana asked at what point an immigrant should decide to buy their first home. Ani's answer was direct:
How do you know an immigrant can buy a house? Because they pay rent. If you pay rent, you're also capable of paying for your house.
She warned that the internet has a lot of incorrect information and that you have to ask yourself what the source is: what that person has done and whether they can prove they did what they are talking about themselves. "If you haven't done something, you can't guide a person in doing it," she said.
She explained that there are home-buying programs with down payments starting at 3.5%. That same day, she said, a client of hers was signing for a large five-bedroom house with about $12,000, with the closing costs covered. He was paying $2,400 in rent and with the mortgage he would be paying $2,480: just $80 more, but now it is his house. And that $12,000 came from the previous year's tax refund.
Ani also mentioned a tax rule few people know about: if you buy a home and live in it as your primary residence for at least two years, when you sell it you can keep the gain, up to certain limits, without paying taxes. That is why she stressed hiring someone who is truly up to date on tax law.
Her conclusion was that everyone can do it, but many people spend their refund on things that make them poorer, like going to the mall. Her question before any purchase is: "Do you want it or do you need it?" If you want it, it can wait. She would rather buy a house that gives her a gain in two years than buy things.
A home to live in or an investment property
Liliana asked which is more profitable: buying properties as investments or a house to live in. Ani, who has bought both, explained the differences:
- Investment: programs usually require a down payment starting at 15% and the interest rate is higher, because the assumption is that the home will be rented out and you will earn a profit.
- Primary residence: someone who is stretching their paycheck can start with a house at 3.5% down, move in, live there for two years and then decide whether to rent it out or sell it, with tax benefits that Ani described as incredible.
And she repeated an idea that comes up in all her interviews: people think the real estate business is about collecting rent, but she does not even pay attention to the rent. What matters most to her is the depreciation of the properties, which lets her pay less in taxes. That, for her, is the real benefit of investing in real estate.
What a good tax preparer should ask
Liliana asked whether any accountant, upon learning that a client bought a house, will apply the corresponding depreciation and exemptions on their own. Ani replied that this should be part of the service, and explained how they do it at her office.
When a new client contacts them, many of them referred by other clients, they fill out a questionnaire that includes questions such as:
- Did you buy any property this year?
- Did you buy any vehicle?
- Did you buy any machinery for your business?
New clients are often surprised because no one had ever asked them. Ani's answer is that, if they bought any of those things, they may be entitled to depreciate them and pay less in taxes. Why do others not tell them? In her view, because it takes more work and many people want to make easy money.
The American system works if you follow the ABCs. If you do everything that's written, you're going to succeed, because here everything is written down.
If you improvise, on the other hand, you miss out on tax credits. As an example, she mentioned a refundable credit from the pandemic era for self-employed workers, including those who received 1099 forms from apps, which many preparers never mentioned to their clients. At her office they reviewed prior returns and, only if it was worth it, explained to the client how much they could receive, so the client could decide whether to file the amendment.
Liliana agreed that a lot is lost through lack of knowledge, and that this is why it is so important to have an ally who wants to do the job right and not simply fill out a form.
First scenario: $5,000 in savings
Liliana proposed an exercise: she would lay out scenarios and Ani would say what she would do if that person came to her office. The first: a legal immigrant who has been in the country for two years and has $5,000 saved.
Ani started by asking whether she had any debt. Liliana clarified that she did not, that she only had one card that she paid in full every month, and that the $5,000 was savings separate from her expenses. Ani explained how she would analyze it:
- Depending on the person's age, she would consider an IUL or a Roth IRA account.
- A Roth IRA also grows with compound interest, but it has requirements, including income limits set by the IRS, so she would first review the person's income and filing status: single, head of household or another status.
- She would also explain that money sitting still loses value: even if the account still shows $5,000, inflation keeps eating away at its purchasing power.
- If the person feels insecure without seeing that money, she would suggest keeping half as a backup and investing the other half according to their situation.
Second scenario: the dream house
The second scenario: a married woman with two children who has the money for the down payment on her dream house. Ani answered with a question:
Do you want your dream house today? Because your dreams today aren't going to be the same dreams as tomorrow.
She would suggest the alternative of first making a quality investment so that, in a few years, she can buy the house she really wants. She explained that the house you live in cannot be depreciated on your taxes; only investment properties can. Her proposal would be to use that money to buy investment properties, rent them out and let the depreciation of those homes serve as a bridge: it helps reduce taxes while the reported income stays high, which later makes it easier to qualify for the house she wants.
Her underlying advice was not to fall in love, because people tend to buy on emotion. It is not that mistakes are always made, she clarified, but you can make better-quality deals for your family.
If the client insists on buying her house, Ani suggests she buy it and live in it for two years, because she is sure that after that time it will no longer be her dream house and she will want another one. She explained that, if the need to move genuinely comes up, for example because the children change schools and the house is far away, you can rent out the previous one and apply for another loan for a new primary residence with a low down payment, as long as there is a real justification and you are going to live in it. She said she herself has moved many times, living in each house. Over time, the bank will ask you for a larger down payment, but by then you will already have built up several properties. Liliana summed up the strategy: you rent out the first one and live in the next, and that way you grow your assets and become very attractive to banks.
How many credit cards to have and why not to close the old ones
Liliana shared her own experience. When she arrived she was given a credit card, she always paid it in full and her credit started to grow. More offers came in and she was advised to accept them. With the fifth card, her score dropped from 770 to 710. She was told she had too much credit and, following other advice, she closed one of her first cards, which had a low limit, because she already had others with much higher limits.
Ani replied that this was false information: it is not true that a lot of credit is bad. She has 12 personal cards, some with limits of just $500, and never plans to close them. She said one of them is a department store card, with very high interest, that she accepted when she arrived because it gave her a big discount on that day's purchase; she took the products home and paid it off a few days later. Today, when she goes to that store with her teenage daughter, she uses that card to keep it active. She has had it for nine years.
Her advice on cards was:
- Do not close old cards. Your score is based on history: if you close a card you have had for a long time, you lose that history and that stability, regardless of the limit.
- Use them once in a while. If you go years without using a card, the bank may close it. Ani buys gas with her personal cards and pays them off within 15 or 20 days.
- Ask for limit increases. Some banks raise the limit online or over the phone without doing a hard inquiry on your credit.
- Have access, but do not use it. Having high limits without using them tells the bank you do not need its money to finance yourself, and that is why it opens doors for you.
- Be careful how you use personal cards. A small charge reported on a personal card can cost you points, because they work differently from business cards.
Liliana asked how many cards is ideal. Ani replied that she does not think there is a fixed limit; she simply stopped accepting personal cards when she felt comfortable with the limits she had.
Business cards at 0%
Ani said many clients ask her how the bank keeps lending to her after she has bought so many properties. Her answer: she has no personal debt. Her companies carry the debt.
She explained that she receives business cards on which she is the guarantor, but with 0% interest for a period of time. She uses that money for the business and pays it off before the period ends, because afterward the interest can be around 30%. That way she pays no interest, and when her personal credit is checked, no debt shows up.
If you have financial discipline, you can do it. Not everyone can do this.
She warned that the risk is that people see a minimum monthly payment, do not plan to pay off the balance before the twelve months are up and end up with a snowball they do not know how to control.
Properties in your name or in a company?
Liliana asked whether it is better to buy houses in your own name or through a company. Ani answered that it depends:
- She holds her investment properties, especially the ones she rents on Airbnb, in companies, because the risk is greater: many more people come through than a family living there for a year.
- If you are going to live in the house, it has to be in your name, because you are receiving the benefit of a low down payment.
- Over time, the bank may allow you to transfer it to a company, but the change has to make sense and must never weaken the collateral. If two people used to pay for the house, you cannot ask for it to now be paid by just one person who earns less.
- If you have never fallen behind and can show that you will keep paying, banks usually allow it.
Liliana commented that it was hard for her at first because she did not have guidance like that, and that finding someone to steer you from the moment you arrive helps you grow faster, because in this country every mistake is paid for in credit points and in money.
One yes and one no about money
Liliana asked her for one yes and one no about what to do with money. Ani said the no was the easiest: stop spending on things that make you poorer. Leave the house every day with a purpose, and do not go wandering around the mall to see what you find, which for her is the worst mistake.
The yes: sit down, take a sheet of paper and make a budget. "If you're organized, there's no way to fail," she said. She also advised setting emotions aside when it comes to money and not worrying about what other people will say.
She shared her own sacrifice: for two years she did not go to the beach without bringing homemade sandwiches, they did not go into restaurants, they did not buy coffee out and they made it at home to take to the office. She promised her family that, once that time was up, they would get to choose where to travel.
You have to be willing to make an initial sacrifice. If you do it, later on, when you're more comfortable financially, it's what comes naturally to you.
Today, she said, she loves eating out and she does it, but she wants to do it without worrying about how much the check will be when the waiter comes. To get there you have to get organized, assign every dollar to its purpose and, once you are on track, set aside more for entertainment. Liliana added that living in anguish over money harms your health and that no one wants a life full of stress.
Three daily routines
Liliana asked her for three routines she has adopted that have changed her life. Ani shared these:
- The list from the night before. She writes down in her phone's notes the things she cannot fail to do the next day, and during the day she checks them off as she gets them done.
- The nightly family meeting. She considers it essential for the whole family to be involved, because it is very hard for one person alone to change a household's habits. Every night she talks with her children about how their day went and what is on each one's mind. Her children have known about finance since they were little and work with her when they do not have classes. She explains things like how leaving the lights on raises the electric bill and that limits their vacations, and she gave her daughter, who loves makeup, a budget she has to stay within. If someone announces they are going to spend it all, she stops them right then and there.
- Checking emails and messages every morning. The first thing she does when she wakes up is check her email. Also, since the company receives between 400 and 500 WhatsApp messages a day, and even though there is a team of eight people handling them, she checks every day that no client has been left without a timely response.
She explained that this last routine has to do with quality of service. She was a mistreated client herself and used it as motivation, but not everyone reacts the same way. Besides, they handle sensitive matters: if they do not act in time, a client can lose money, and those mistakes are very costly. Liliana related to this, because she also checks every day that her team responds to every patient.
If she lost everything
Liliana asked whether she could recover if she lost everything she has achieved. Ani replied that it would not worry her, because she knows how to recover quickly, and she estimated that she could easily do it in a year.
She said money is no longer a worry for her, and that now she wants her whole team to grow financially: two people on her team have already bought their properties and are working on their second. She stressed that it is not about going from one point to another overnight, but about starting with commitment, focus and discipline. She has clients who drive for Uber, without a company of their own, who are already on their second house.
Do you want one minute of happiness today, or do you want to tell your family: pick the place you want to go on vacation?
For Ani, buying something that brings you poverty is harming yourself, and loving and valuing yourself also means thinking before you spend. She noted that family vacations are necessary to spend time together and clear your mind, but that you cannot enjoy them with financial problems.
Health, money and love, from one to ten
Living up to the podcast's name, Liliana asked her to rate the three pillars of her life.
Health: 9. Ani explained that she takes care of herself, goes to her checkups and stays on top of it, but that during tax season she does not keep regular mealtimes or get enough sleep. Liliana reminded her that money is worth nothing if lack of sleep ends up affecting your health.
Money: 10. She clarified that this is not because she has reached a final goal, since she will always keep dreaming and growing, but because she has no worries about making payments. Over the years she built a financial cushion to cover the mortgage for a good while if something serious happened, so she does not live in fear about her family's expenses. Even so, she has many aspirations: she wants the company to keep growing and the people who work with her to grow as well. She tells them every day to learn everything they can, because when the company opens new offices she wants them to be run by people who were once her clients, people with potential who perhaps have not had the chance to leave the apps and get trained in an office. They always try, she said, to support the same people who have supported them for years.
Love: 8. Ani explained that for her love is not just about a partner or just about your children, but about the way you relate to people in general.
The final message
Liliana thanked her and asked for one last message for the audience. Ani left it like this:
Even if your reality today isn't what you hoped for, believe me, if you take responsibility, sit down with your family with a sheet of paper and a pencil, start writing down all your debts, all your obligations and all your income, and get organized, you're going to be able to get ahead.
Ani said people can find her as Ani Miller Services on YouTube, Instagram, Facebook and TikTok.
This episode of Salud, Dinero y Amor is one of Ani's most practical conversations: it moves from her personal story, from Venezuelan banking to delivery apps, to concrete tools such as building credit without closing old cards, insisting that your tax preparer ask about properties and vehicles, using depreciation and buying your first home with strategy and without getting carried away by emotion. The underlying thread is always the same: get organized, make an initial sacrifice and follow the plan with discipline.
Video: Salud, Dinero y Amor channel and podcast with Liliana Pérez.
This article is an English translation of the original Spanish version. Quotes have been translated from Spanish. Leer en español.
BOOK A VISIT
Let’s talk about your money
Leave your details and we will call you to understand your situation. We speak English and Spanish.
KEEP READING
More from the blog
“Trust Doesn't Mean You Stop Asking”: Ani Miller on La Mesa Caliente
On La Mesa Caliente, Ani Miller explains why handing all your finances to your partner can leave you vulnerable.
Read →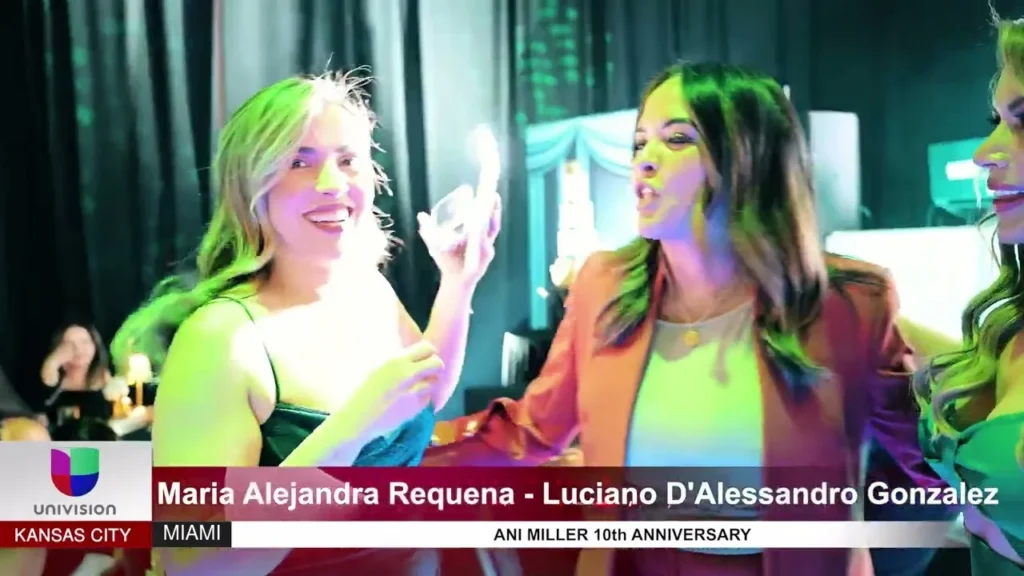
Ani Miller Services Turns 10: Univision KUKC’s Coverage
Univision KUKC was at the 10th anniversary celebration of Ani Miller Services with friends, family and clients.
Read →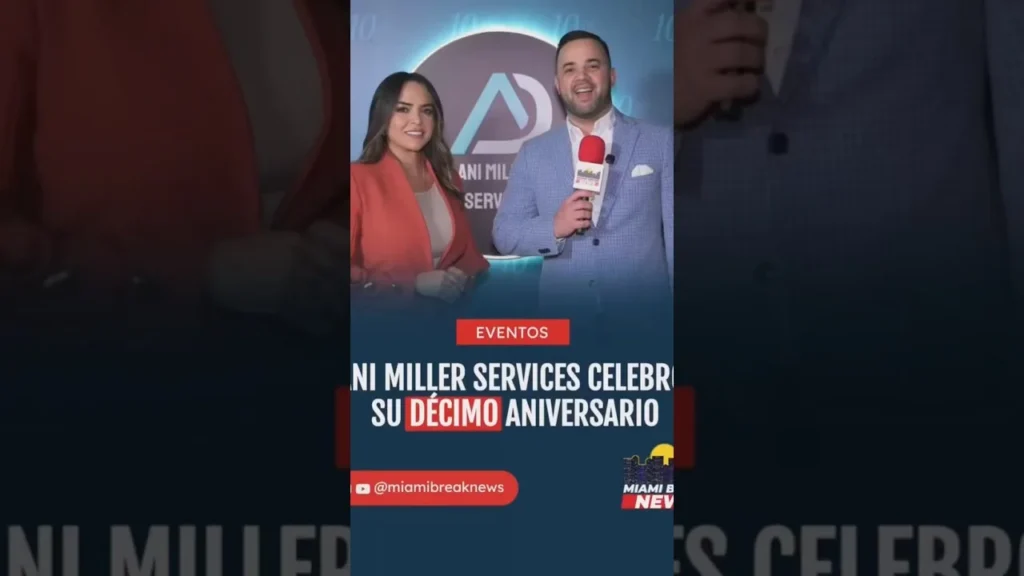
“Focused Discipline”: Ani Miller Services Celebrates 10 Years
Ani Miller celebrated her company's 10 years and her 39th birthday in Miami, and shared the key to her journey.
Read →YOUR NEXT STEP
Before you make an important decision about your money, talk to Ani.
A financial intelligence firm for individuals, families and business owners. In English and Spanish.
Notary Public. I AM NOT AN ATTORNEY LICENSED TO PRACTICE LAW IN THE STATE OF FLORIDA, AND I MAY NOT GIVE LEGAL ADVICE ABOUT IMMIGRATION OR ANY OTHER LEGAL MATTER OR ACCEPT FEES FOR LEGAL ADVICE.
© 2026 Ani Miller Services · Inversiones Los Palapunes Corp.
Ani Miller Services